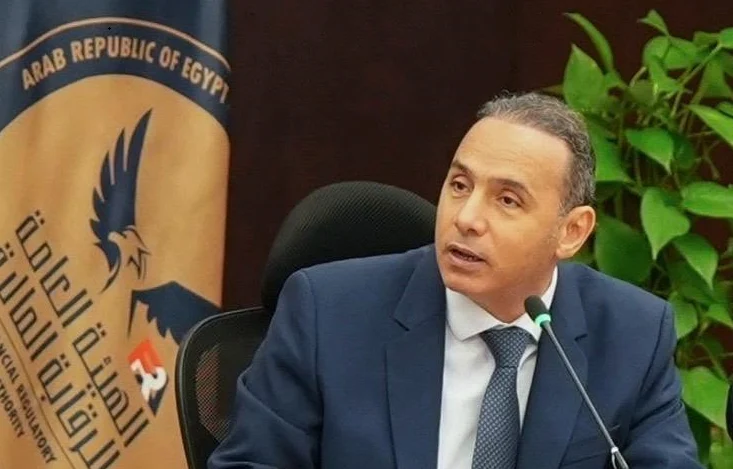
Rana Mamdouh _ Dr. Islam Azzam, Chairman of the Financial Regulatory Authority (FRA), issued a decision regarding the model form of contracts between brokerage firms and borrowing clients, in a new step paving the way for the anticipated official launch of the "short selling" mechanism (borrowing securities for the purpose of selling / selling borrowed securities) in light of the new regulatory framework recently issued by the FRA's Board of Directors Decree No. (155) of 2026.
The decree aims to establish a clear contractual framework governing the relationship between the borrowing client—who wishes to borrow securities for the purpose of selling, which are available through the central lending system at the Central Depository and Registry company (Misr for Central Clearing, Depository and Registry) and the brokerage firm licensed to conduct operations—conducted on behalf of the borrowing client.
The "short selling" mechanism is based on the presence of a "lending client" who wishes to lend shares owned by them, and a "borrowing client" who wishes to borrow shares to trade them by selling and then buying them back at a later time and returning them to the lender if they expect their price to decline. Thus, profit is achieved through the difference between the selling and buying prices, based on the investor's expectations of market changes and the security price, pursuant to an agreement between the investor and one of the brokerage firms licensed to conduct these operations.
The issuance of the model form of the contract came under the FRA Chairman's Decree No. (3350) of 2026 after consultation with market stakeholders, to benefit from the expertise of companies operating in the activity and determine the requirements for practical implementation. This reflects the FRA's steadfast approach of establishing a constructive societal dialogue, which helps develop enforceable regulations that achieve a balance between facilitating the practice of the mechanism, managing its risks, and protecting clients' rights.
The model form of the contract determines the obligations and rights of both the brokerage firm and the borrowing client, their procedural roles, and regulates expenses, commissions, returns on investment of the margin collateral, and the method of its distribution. This supports the efficiency of the practical implementation of the mechanism, enhances clients' ability to understand the mechanism and its associated risks, monitor the margin collateral, and take necessary measures to close positions when cases specified contractually or regulatory occur.
The contract model sets controls for managing the risks associated with the operation, foremost among which are the collaterals provided by the borrowing client, where the client is committed to providing the margin collateral according to the percentages specified in the contract annex prior to the execution of the borrowing transaction, and at a minimum the percentages set forth in the FRA's decree. Meanwhile, the brokerage firm is committed to depositing the cash collateral in a separate account dedicated to short selling operations.
With the objective of mitigating risks associated with the operation and safeguarding clients' rights, the contract model stipulates obligating the brokerage firm to revalue the borrowed securities according to the instantaneous closing price during the trading session, and to monitor the ratio of total collateral to the value of the borrowed securities in accordance with the percentages specified in the contract annex, and at a minimum the percentages set forth in the decree.
It also regulates handling cases of failure to return the borrowed securities on the specified date, as the brokerage firm is obligated to buy the securities necessary for the return, taking into account the relevant settlement dates, as well as cases of closing positions, including the removal of the security from the list of securities permitted to be traded through the mechanism, and the issuance of regulatory decisions or approvals related to acquisition, merger, tender offers, division, liquidation, or other operations determined by the FRA.
Determining the Obligations and Rights of Both Parties, Controls for Managing Collaterals, and Closing Open Positions
The company must also deliver to the client a detailed guide clarifying the concept of borrowing securities for the purpose of selling, its basic provisions, procedures, advantages, and associated risks. It must also update the guide upon making any amendments to the regulating decisions, provided that it is presented to the client at least once annually and upon each update.
The contract stipulates that the investment of the cash collateral margin must be in instruments determined by the FRA throughout the lending period, with the brokerage firm being obligated to notify the client of the investment avenues and actual return, and to add the return to their account upon collection, or in accordance with the agreed-upon terms.
Regarding the cost of borrowing, the model obligates the company to include all expenses, commissions, and other cash amounts deducted from the client, stating the basis for calculating each of them, while prohibiting any future modification of commissions and expenses except with explicit approval from the client.
The model guarantees the client the right to issue orders to buy and sell borrowed securities, and to close their open position wholly or partially during the borrowing period in accordance with the contract terms.
Ongoing Societal Dialogue with Market Stakeholders to Complete Regulatory Aspects in Parallel with Live Testing of the Central Lending System
Dr. Islam Azzam, Chairman of the Financial Regulatory Authority (FRA), stated that the model contract form represents a new step towards launching the "short selling" mechanism, as the FRA is working on completing the regulatory aspects and practical guidelines for all participants in the mechanism, in parallel with putting the final touches on the central lending system prepared and managed by Misr for Central Clearing, through live testing. This aims to ensure complete real-time integration between the system and brokerage firms, document all work stages and procedures, enable borrowing clients to view all lending offers available from lending clients and choose what aligns with their investment objectives, and also enable the lending client to view all other lending offers recorded through the system.
The Chairman of the FRA added that the model contract form aims to facilitate operations for brokerage firms and borrowing clients, regulate the relationship between them, and unify the contractual basis in light of the regulatory framework of the mechanism. It also extends to defining responsibilities related to managing collaterals, monitoring open positions, and handling cases of declining collateral value or delays in returning borrowed securities, in order to safeguard the rights of all parties.
He pointed out the necessity for the contract to include the borrowing client's acknowledgment that they are the original owner and sole beneficiary of opening the account, the legality of the sources of their funds, and that they fulfill the relevant data requirements in accordance with Anti-Money Laundering Law No. (80) of 2002 and regulatory decisions issued regarding combating money laundering and terrorist financing in non-banking financial activities.
Dr. Islam Azzam clarified that brokerage firms licensed to conduct operations are committed to maintaining data confidentiality, privacy of information, and documents related to clients, and not disclosing information about them or their transactions to third parties without prior written consent and within the limits of that consent, except in cases related to notifying the FRA of specific data or information or pursuant to a court order in accordance with relevant legislation.
It is worth noting that the borrowing client in the "short selling" mechanism profits in the event that their expectations of a decline in the price of the borrowed securities are met, as they buy them back, realizing the profit percentage, and return them to the lender, with the borrowing cost deducted from the profit. As for the event of a rise in the security price and the borrower's desire to stop their losses, they repurchase the securities, incurring a loss, and return them to the lender, with the borrowing cost added thereto.
In both cases, the lender receives a return resulting from lending their securities that is close to the risk-free rate, in addition to the required return for lending, and other advantages resulting from owning the shares.