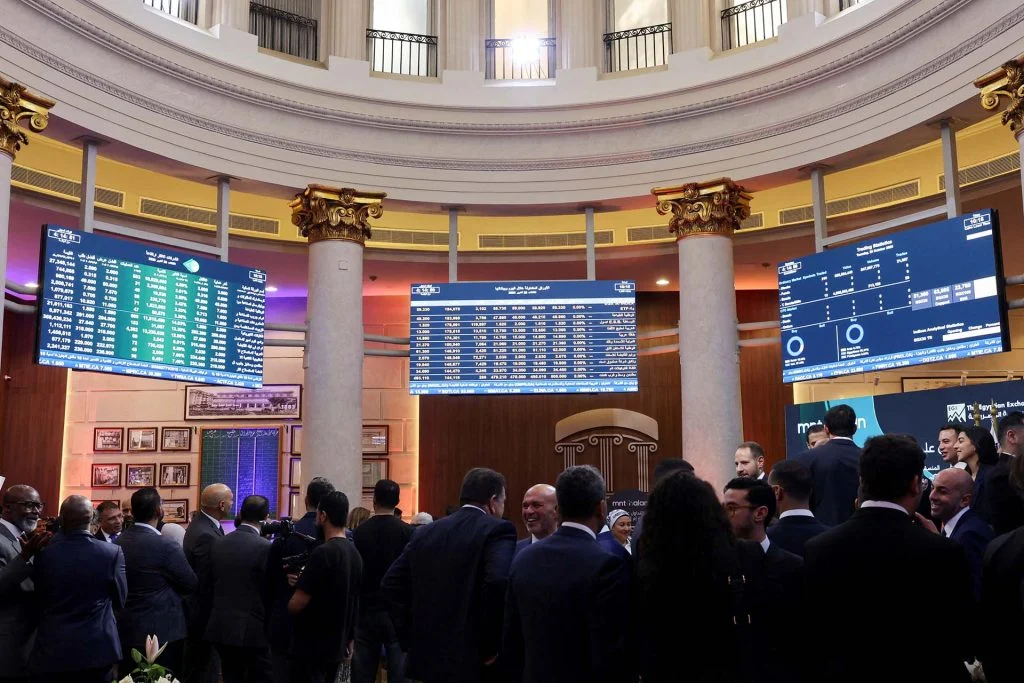
The size of Egypt's investment fund sector exceeded EGP 500bn during the third quarter of 2026, according to an announcement by the Financial Regulatory Authority (FRA) last Sunday—the same day the EGX70 index lost around 11.07% of its value in a single session. The net asset value (NAV) of funds rose by 7.16% quarter-on-quarter to reach EGP 504.71bn compared to EGP 470.97bn, while assets under management (AUM) surged by 7.27% to EGP 512.84bn, according to the FRA's Q3 report (PDF), coinciding with the launch of 8 new funds that raised the total number of funds to 232. None of this growth stemmed from new cash inflows into money market funds, which account for 60% of the sector's assets; rather, the capital attracted was less than their cumulative returns, signifying net outflows.
Retail investors almost completely dominated purchasing activity, which is clearly evident in the volume of certificates rather than cash liquidity; the number of outstanding fund certificates jumped by 19.21% to 52.50bn certificates, with retail investors holding 41.90bn certificates, up from 32.90bn certificates at the end of June. This volume pushes their share up to 79.8% compared to 74.7% in the previous quarter. Conversely, institutional investors moved in the opposite direction, holding 10.16bn certificates compared to 10.72bn certificates three months prior, causing their share to drop to 19.4% from 24.3%. Fund founders retained the remaining 0.8%, representing 441.7mn certificates. Nevertheless, it is worth noting that the number of certificates and fund assets represent two different metrics; for instance, holding 79.8% of certificates does not translate to holding the same 79.8% share of Egypt's EGP 500bn investment fund industry.
At the asset level, the sector's core pillar remained virtually unchanged. Money market funds, accounting for nearly 60% of the total, grew by 2.1% to reach EGP 303.12bn compared to EGP 296.90bn at the end of June. Ahmed Abou El Saad, Managing Director of Azimut Egypt, told Enterprise Morning Digest that an asset base of this scale naturally grows by around EGP 12bn to 13bn each quarter due to cumulative returns without selling any new certificates, whereas this category only grew by approximately EGP 6bn. Abou El Saad added: "This indicates that there were actually net outflows from these funds." He also considers these withdrawals reflective of corporate entities proceeding to draw down liquidity previously held to shift into Treasury Bills or cover working capital requirements, emphasizing that it is not a structural shift, but merely routine redemptions.
In pursuit of higher returns, this liquidity redirected its destination. Traditional equity fund assets stood at EGP 36.01bn by the end of September, and Islamic equity funds at EGP 22.82bn, combining for EGP 58.83bn—a figure close to Abou El Saad's estimate of EGP 59bn for both categories. Index funds recorded the fastest growth, surging by 82.6% to EGP 13.14bn, followed by precious metals funds with a 26.6% growth to EGP 11.92bn. Foreign currency funds also attracted inflows of around EGP 8bn, boosting their assets by 31% to the equivalent of EGP 34.60bn, which raised their market share to 6.9% from 5.6%, compared to EGP 470.10bn for EGP-denominated funds.
Fund returns dipped alongside the cooling momentum of the Egyptian Exchange rally, though this did not apply across all categories. Equity funds delivered an average return of 5.55% compared to 17.66% in Q2, while thematic funds dropped to 5.68% from 18.78%, and sector funds achieved a 12.23% return, having previously led Q2 performance with an 18.82% return. Islamic equity funds recorded an 8% return compared to 16.37%, and precious metals funds achieved 8.23%. Private equity funds led the quarter with a 15.24% return, followed by index funds at 13.03%, outperforming the EGX30 index which rose by only 2.79% during the quarter. Abou El Saad believes that a profit-taking wave was inevitable following a continuous rally, commencing in September.
Index Funds
The 13.03% return generated by index funds is credited to the EGX70 and EGX100 indices, which rose by 20.14% and 17.19% respectively in Q3, while the main index made little progress. Abou El Saad views this as a methodological issue; both indices rely on equal weighting, meaning Commercial International Bank (CIB) carries the exact same weight as the stock ranked 100th on the list. Abou El Saad remarked: "When massive inflows arrive, capital is forced to blindly flow into these lower-tier stocks, unjustifiably inflating their valuations," noting that many constituent stocks of both indices are unsuitable for investment based on their earnings, and that the specific reason behind retail interest in purchasing them is simply that they had already appreciated. The test arrived in October, when the EGX70 index lost around 11.07% in a single session on Sunday, October 25, and the EGX100 fell by 8.88%. Even following a 7% market rebound on Tuesday, both indices remained below their Q3 closing levels by 12.34% and 10.65% respectively at the end of Wednesday's trading, compared to a 5.04% decline for the EGX30.
Context: Most retail investor capital entering funds does not flow into the stock market in the first place; 85% to 90% goes toward money market funds or fixed-income products, according to what Himanshu Shrimali, CEO of Thndr Holding, told us last month. He attributed household aversion to equity products to a knowledge gap and the observed one-directional trend of the Egyptian Exchange over the past five years. Retail investors accounted for 72.7% of total trading in listed equities during H1 2026—a pattern Mohamed Abu Basha, Chief Economist at EFG Hermes, views as closer to frontier market characteristics than an emerging market.
Next Step: Abou El Saad expects growth momentum to persist in Q4, supported by the establishment of new funds and asset classes, particularly as the size of the investment fund sector remains modest relative to GDP and bank deposits by global standards. Further fund launches are anticipated, with the Financial Regulatory Authority (FRA) and the Egyptian Exchange (EGX) working to amend Article 29 of the Capital Market Law to permit limited liability companies and simple limited partnerships to obtain licenses for establishing funds. Meanwhile, the EGX seeks to expand tax-exempt fund categories up to 38, while the first regulatory framework for hedge funds issued by the FRA came into force in September.
Caveat on Figures: The Financial Regulatory Authority (FRA) reclassified investment funds in collaboration with the Egyptian Investment Management Association (EIMA) in Q2, raising the number of funds at the end of March from 187 to 209 funds and re-estimating the NAV at around EGP 411bn. Consequently, comparisons with periods prior to that date are not entirely precise. However, this does not alter the nature of what was actually sold; the vast majority of the EGP 500bn remains in money market funds.